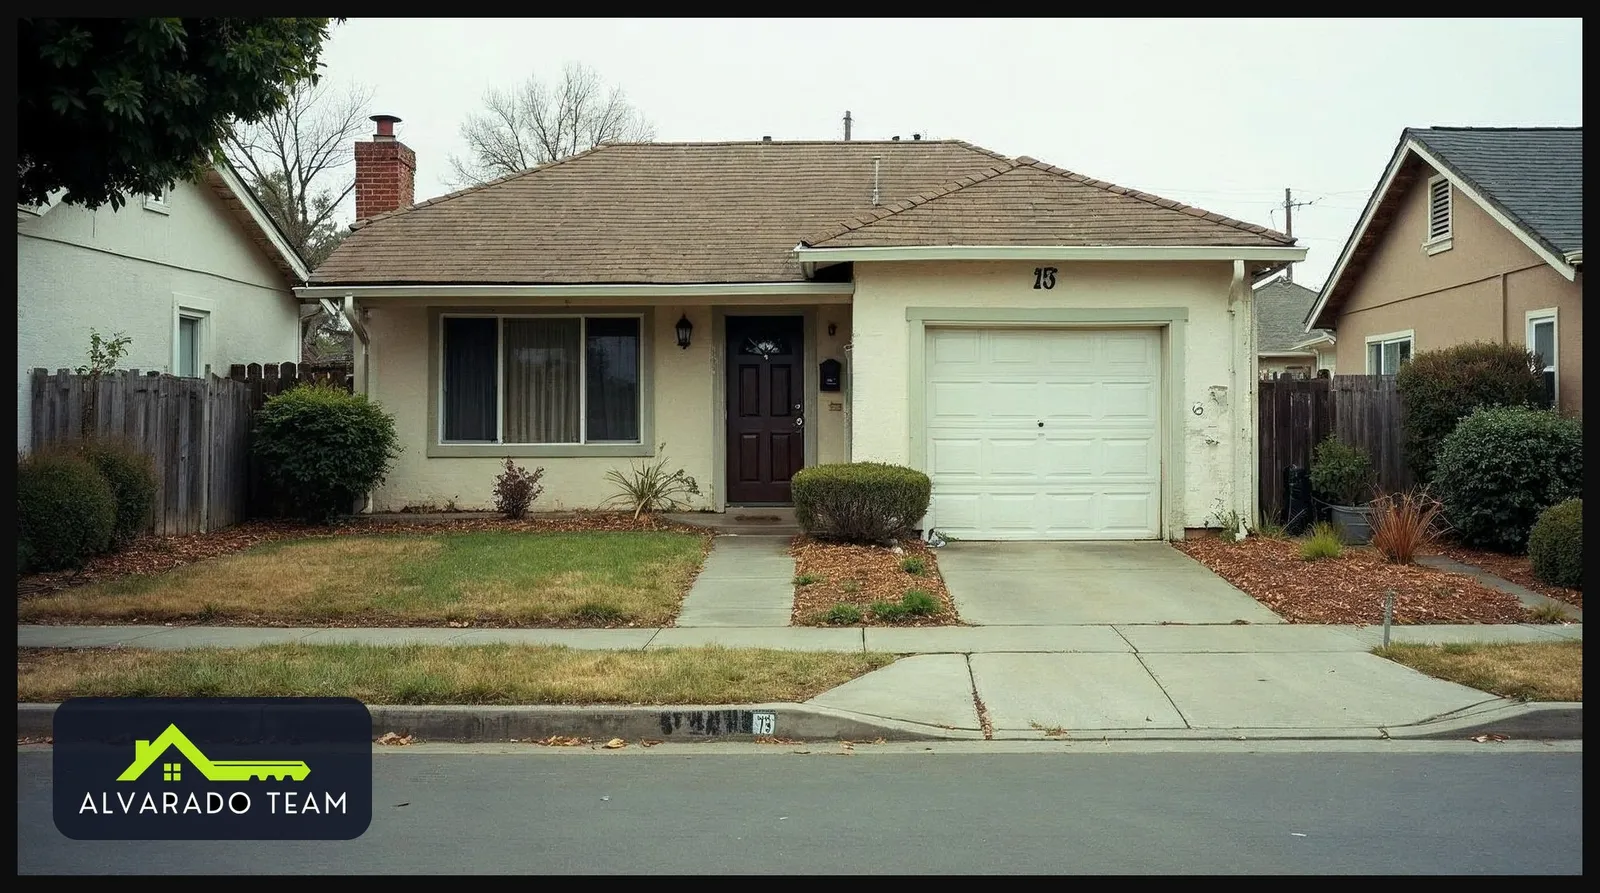
If you are shopping for Fairfield CA foreclosure homes, the biggest mistake is assuming a low price automatically means a good deal. Foreclosures can create real opportunities, but they can also come with title issues, repair surprises, and a slower offer process than a traditional sale.
Before you make an offer, you need to understand how the property is being sold, how much risk you are taking on, and what to check first. In Fairfield, the right approach can help buyers, investors, and even first-time purchasers avoid expensive missteps.
What makes Fairfield CA foreclosure homes different
A foreclosure is not the same as a standard resale. In many cases, the lender or bank is selling the property after the owner has fallen behind on payments. That means the home may have been vacant, poorly maintained, or caught in a process that limits what the seller will disclose or repair.
- The property may be sold as-is, with little or no repair credit.
- Showings can be limited, especially if the home is occupied or bank-owned.
- Offer timelines can be slower because multiple parties may need to review documents.
- Some homes have unpaid taxes, liens, or title issues that must be resolved before closing.
For buyers in Fairfield, that means the purchase is not just about price. It is about condition, timing, financing, and risk management. A lower list price can still be a bad deal if the repair budget is unknown or the closing process drags on.
How to evaluate a foreclosure before you offer
The most important step is to evaluate the home as if the asking price is only one part of the total cost. Look at the property’s condition, market value, location, and likely repairs before you decide what to offer.
- Compare the home to recent Fairfield sales, not just nearby active listings.
- Estimate repairs realistically, including roof, HVAC, plumbing, electrical, flooring, and cosmetic updates.
- Check whether the property is occupied, vacant, or tenant-occupied.
- Review title, tax, and HOA information early if possible.
- Decide in advance whether this is a buy-and-hold investment, a primary residence, or a flip.
If you are working with a Fairfield Real Estate Agent who knows local foreclosure inventory, ask for a clear price analysis. The best offer is usually the one that reflects true after-repair value, not emotion or competition alone.
Financing and cash considerations
Your financing strategy matters as much as the property itself. Some foreclosure homes can qualify for conventional, FHA, or VA financing, but many lenders require the home to meet minimum condition standards before they will fund the loan.
- Cash offers are often stronger because they can close faster and with fewer loan conditions.
- Conventional financing may work if the home is in livable condition.
- FHA and VA loans can be more limited if the property needs major repairs.
- If the home needs work, a renovation loan may be worth discussing with your lender.
If you are an investor, cash or hard-money financing may give you more flexibility, but you still need a disciplined offer number. A deal that looks cheap can become expensive if repair costs or holding costs are underestimated.
Inspection issues buyers should not ignore
Even when a foreclosure is sold as-is, inspection due diligence still matters. You may not get the seller to fix anything, but you can decide whether the home is worth pursuing, renegotiate if allowed, or walk away before you are locked into a bad purchase.
- Look for signs of water intrusion, roof damage, and mold.
- Check HVAC, water heater, electrical panel, and visible plumbing.
- Watch for deferred maintenance caused by vacancy or neglect.
- Inspect windows, siding, grading, and drainage around the property.
- If the home has been vacant, verify whether pests or vandalism are an issue.
A foreclosure can look fine on the surface and still need major work underneath. That is why experienced buyers use inspections, contractor input, and conservative budgeting before they submit a final offer.
How to structure a smart offer
Your offer should be based on numbers, not just the asking price or a perceived bargain. In Fairfield, sellers and lenders respond better to clean, well-documented offers that show you understand the property and can close.
- Include proof of funds or a strong pre-approval letter.
- Keep contingencies realistic, but do not remove them too early.
- Offer a price that leaves room for repairs and closing costs.
- Use an earnest money deposit that shows seriousness without overexposing yourself.
- Be clear about your closing timeline and whether you need extra time for inspections or financing.
If multiple offers are in play, the cleanest offer is not always the highest. A faster close, fewer contingencies, and solid financing can matter just as much as price, especially in competitive Fairfield CA foreclosure homes searches.
Mistakes to avoid when buying foreclosure homes in Fairfield
Many buyers lose money on foreclosures because they focus on the discount and ignore the details. Avoiding a few common mistakes can protect your budget and save you time.
- Do not assume every foreclosure is a bargain.
- Do not skip title and lien research.
- Do not underestimate repair and holding costs.
- Do not rely only on photos, especially if the home is vacant.
- Do not remove contingencies before you understand the risks.
The best buyers are patient, data-driven, and willing to walk away if the numbers do not work. That discipline is especially important in a market like Fairfield, where location, condition, and resale potential can vary from one neighborhood to the next.
Frequently asked questions
Are Fairfield CA foreclosure homes always sold as-is?
Often, yes, but the exact terms depend on the seller, the lender, and the property condition. As-is usually means you should expect limited repairs, if any, from the seller.
Can I finance a foreclosure with an FHA loan?
Sometimes. The home must usually meet lender condition requirements, so severe damage or safety issues can make FHA financing difficult. Ask your lender early.
What should I check first before offering on a foreclosure?
Start with comparable sales, repair needs, title concerns, and your financing limits. Those four factors will tell you whether the property is worth a closer look.
Work with a local team before you make an offer
Buying Fairfield CA foreclosure homes takes more than finding a low list price. You need local market knowledge, an accurate pricing strategy, and a clear plan for inspections, financing, and resale value.
Team Alvarado has been selling and listing properties in Fairfield since 2000 and investing locally since 2005. If you want help evaluating a foreclosure, comparing offers, or spotting red flags before you commit, reach out to Team Alvarado for practical guidance specific to the Fairfield market.